 PIPAVO Team
Learn how to choose risk per trade, size Forex positions, control drawdowns, and account for leverage, slippage, costs, and correlation.
In this article
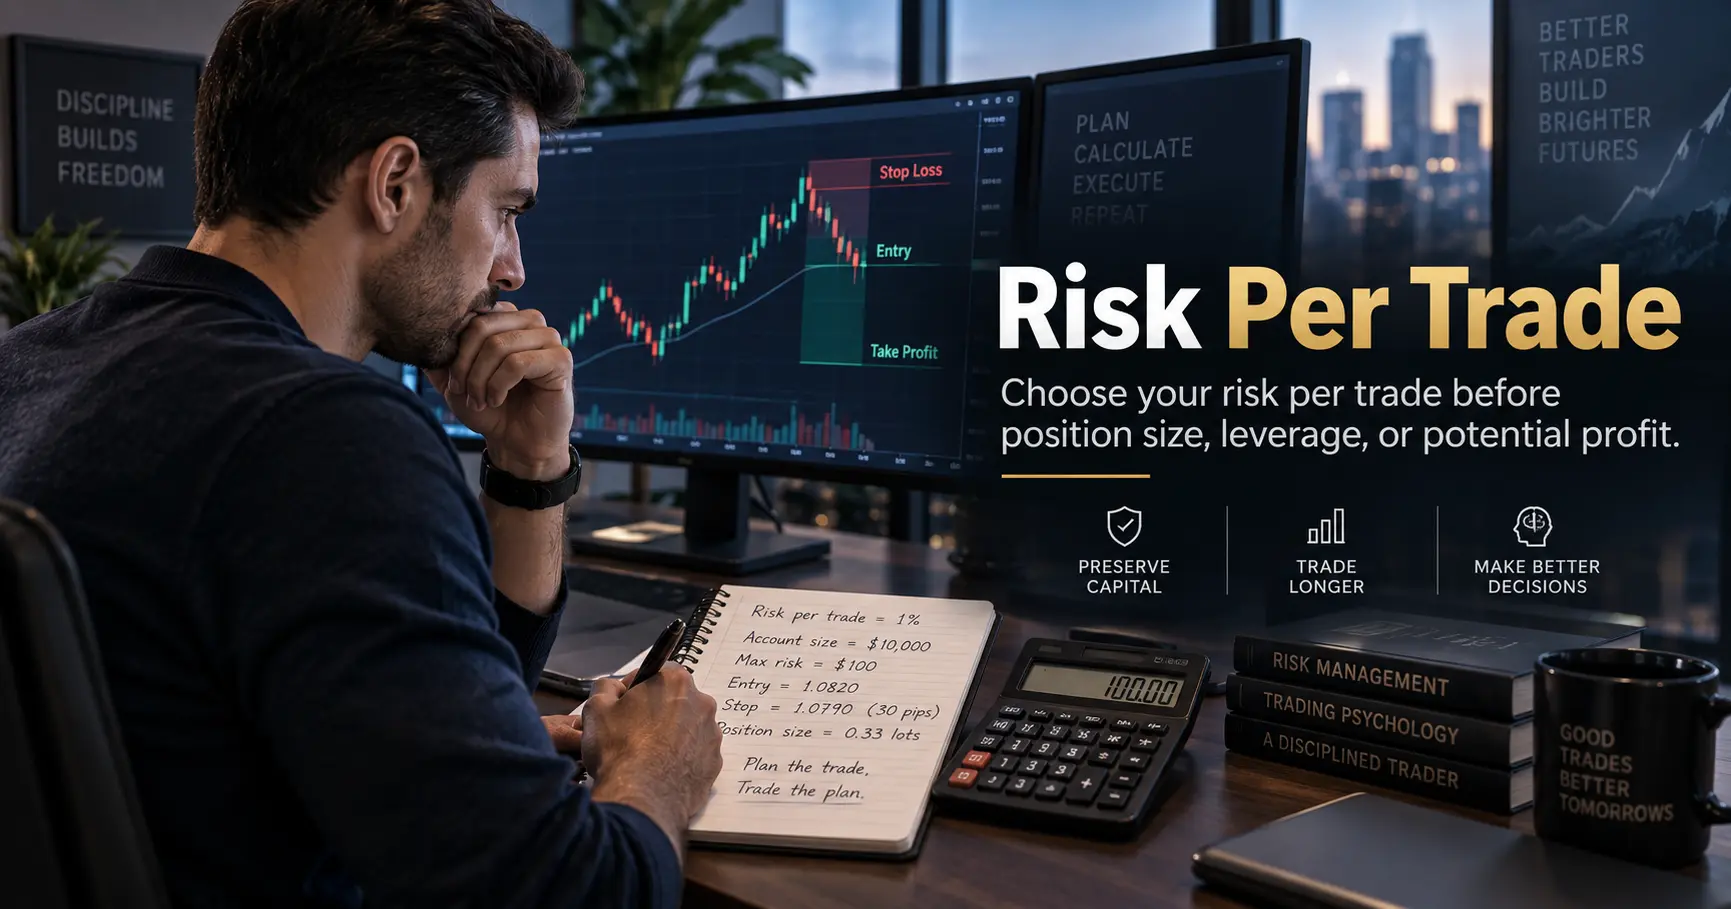
For many retail Forex traders, risking 0.25%–1% of current account equity per trade is a cautious starting range; 1%–2% is a common guideline, not a universally safe rule. The right risk per trade depends on your drawdown limit, strategy evidence, trading frequency, execution costs, and total exposure—not simply how confident you feel about the next setup.
As of 2026, the CFTC reports that roughly two in three US retail Forex traders lose money each quarter. Its 2024 review found that 50.96%–74% of retail self-directed Forex accounts lost money across six registered providers. These figures are not global performance statistics, but they show why capital preservation deserves priority over rapid account growth. (CFTC, 2024; CFTC Forex Frauds)
How Much Should You Risk per Trade?
No percentage is automatically safe. For an inexperienced trader or an insufficiently tested strategy, 0.25%–0.5% of current equity may provide more room for mistakes and losing streaks. One percent is a widely used reference point. Two percent can produce substantial drawdowns when losses cluster and should not be treated as a default.
The following amounts are arithmetic examples, not individualized recommendations:
| Account equity | 0.25% risk | 0.5% risk | 1% risk | 2% risk | 5% risk |
|---|---|---|---|---|---|
| $1,000 | $2.50 | $5 | $10 | $20 | $50 |
| $5,000 | $12.50 | $25 | $50 | $100 | $250 |
| $10,000 | $25 | $50 | $100 | $200 | $500 |
| $25,000 | $62.50 | $125 | $250 | $500 | $1,250 |
A practical framework is:
- 0.25%–0.5%: Consider this when learning, trading a new system, recovering from a drawdown, or managing several related positions.
- 1%: A common planning ceiling for a trader with documented rules and positive results after realistic costs.
- 2%: Potentially aggressive when applied repeatedly, particularly with frequent or correlated trades.
- 5%: Exposes the account to severe compounding damage during an ordinary losing sequence.
“Small” must also be assessed in personal terms. A $100 loss may be mathematically modest in a $10,000 account but financially inappropriate if that capital is needed for rent, debt payments, emergencies, or other essential expenses.

What Risk per Trade Actually Means
Risk per trade is the amount of account equity you plan to lose if price reaches the level that invalidates your trade idea.
The basic formula is:
Risk amount = Current account equity × Risk percentage
If current equity is $10,000 and risk is 1%:
$10,000 × 0.01 = $100 maximum planned risk
Use current equity rather than the original deposit or a higher historical balance. Equity reflects realized account balance plus open profit and loss. If the platform displays $10,000 as balance but equity has fallen to $9,500, 1% of current equity is $95—not $100.
Risk amount is not position size
A $100 risk budget does not tell you whether to trade 0.10, 0.50, or 1.00 lot. Position size depends on the distance from entry to stop, pip value, account currency, and trading costs.
A wider stop should normally produce a smaller position:
| Trade | Stop distance | Pip value at chosen size | Planned price loss |
|---|---|---|---|
| A | 20 pips | $5 per pip | $100 |
| B | 50 pips | $2 per pip | $100 |
| C | 100 pips | $1 per pip | $100 |
All three trades carry the same planned price risk even though their position sizes differ.
Risk, leverage, margin, and exposure are different
| Term | What it measures | Example |
|---|---|---|
| Risk amount | Intended loss at the stop | $100 |
| Position size | Units or lots traded | 50,000 units |
| Notional exposure | Total value controlled | Approximately $50,000, depending on the pair |
| Leverage | Exposure relative to account capital or margin | For example, 5:1 effective exposure |
| Required margin | Collateral reserved by the broker | Determined by leverage and broker rules |
| Free margin | Equity still available after required margin | Platform-dependent |
Suppose a broker reserves $1,000 of margin for a position. That does not mean the position risks only $1,000 or must risk the full $1,000. The loss depends on how far price moves, position size, execution, and whether the trade is closed.

Why the 1% Rule Is a Starting Point, Not a Law
The 1% rule is designed to make any single loss manageable. It cannot turn an unprofitable strategy into a profitable one, guarantee that a stop will fill as planned, or account for several correlated positions.
Risk should usually be lower when:
- The strategy has a short or unreliable track record.
- Results come from a small or over-optimized backtest.
- The strategy trades frequently.
- Several positions depend on the same currency or event.
- Spreads or slippage are unstable.
- The account is already in drawdown.
- A daily or maximum-loss rule is close to being breached.
Using 1% or more requires stronger evidence: a sufficiently representative trade record, positive expectancy after costs, known losing-streak behaviour, and enough drawdown capacity to tolerate worse conditions than those previously observed.
Leverage rules do not define appropriate trade risk
Regulatory leverage limits illustrate the distinction between permitted exposure and sensible account risk.
In the United States, the NFA rule effective March 18, 2026 requires security deposits of at least 2% of notional value for transactions involving ten listed major currencies and 5% for other currency transactions. These percentages imply leverage ceilings of 50:1 and 20:1. They are margin requirements—not recommendations to risk 2% or 5% on a trade. (NFA Financial Requirements, 2026)
In the United Kingdom, FCA rules introduced in 2019 limit retail CFD leverage to between 30:1 and 2:1, require account-level close-out when funds fall to 50% of required margin, and provide negative-balance protection. Negative-balance protection limits certain account-level losses; it does not make individual trades safe. (FCA PS19/18, 2019)
Rules vary by jurisdiction, product, and client classification. Traders should verify their regulator’s rules and their broker’s current contract specifications.

How Losing Streaks Change the Answer
A risk percentage that feels harmless on one trade may become damaging when losses occur consecutively.
With fixed-fractional sizing, the same percentage is recalculated from the remaining equity. After (n) consecutive losses:
Remaining equity = Starting equity × (1 − risk fraction)ⁿ
The table shows the percentage of starting equity remaining after hypothetical consecutive losses. It assumes exact stop execution and excludes spread, commission, swaps, and slippage.
| Risk per trade | After 5 losses | After 10 losses | After 15 losses |
|---|---|---|---|
| 0.25% | 98.76% | 97.53% | 96.32% |
| 0.5% | 97.52% | 95.11% | 92.76% |
| 1% | 95.10% | 90.44% | 86.01% |
| 2% | 90.39% | 81.71% | 73.86% |
| 5% | 77.38% | 59.87% | 46.33% |
After ten losses, 1% risk produces a 9.56% drawdown. At 2%, the drawdown reaches 18.29%. At 5%, it exceeds 40%.
Drawdown recovery is asymmetric
A loss and the gain required to recover it are not equal because recovery begins from a smaller capital base.
| Drawdown | Gain required to return to breakeven |
|---|---|
| 10% | 11.1% |
| 20% | 25% |
| 30% | 42.9% |
| 50% | 100% |
This is why “I can earn it back” is not a risk plan. Larger drawdowns require disproportionately larger recoveries.
Deriving risk from a drawdown limit
Assume a trader decides that ten consecutive full losses should not produce more than a 15% drawdown. Ignoring costs and slippage:
Maximum theoretical risk fraction
(= 1 - (1 - 0.15)^{1/10})
(≈ 1.61%)
That does not mean 1.61% is appropriate. Ten losses may not be the worst sequence, trades may be correlated, and actual losses can exceed planned losses. A trader might therefore apply a substantial safety margin and select 0.5%–1%, depending on evidence and personal capacity.
Historical win rate cannot guarantee the length of future losing streaks. Market regimes change, trade outcomes may not be independent, and a backtest can omit execution problems.

How to Calculate Risk per Trade and Position Size
Use the following order of operations.
1. Calculate the risk budget
For a hypothetical $10,000 account risking 1%:
$10,000 × 1% = $100
2. Define the invalidation point
The stop belongs at the price where the setup is no longer valid—not at an arbitrary distance that produces an attractive lot size.
Assume:
- Hypothetical EUR/USD entry: 1.1000
- Stop: 1.0980
- Distance: 20 pips
3. Calculate position size
The general formula is:
Position size in lots = Risk amount ÷ (Stop distance in pips × Pip value per standard lot)
OANDA’s current product documentation states that one standard retail Forex lot is 100,000 units. For EUR/USD, one pip on 100,000 units is $10 when profit and loss are denominated in US dollars. Broker definitions and minimum increments should still be verified. (OANDA lot specifications, accessed 2026; OANDA pip-value example, accessed 2026)
For the hypothetical trade:
$100 ÷ (20 × $10) = 0.50 standard lot
At 0.50 lot, EUR/USD has a pip value of approximately $5:
20 pips × $5 = $100 planned price loss
This calculation excludes costs and adverse execution. If the full account-risk ceiling is $100, the position should be reduced to leave room for those items.
4. Convert pip value when necessary
The simple $10-per-pip convention works for a standard EUR/USD lot in a USD-denominated account. It does not apply universally.
If the account currency differs from the pair’s quote currency:
- Calculate profit or loss in the quote currency.
- Convert that value into the account currency using the applicable exchange rate.
- Recalculate when exchange rates move materially.
- Confirm the platform’s displayed pip value before placing the order.
Cross pairs and JPY pairs require particular care. A position-size calculator is useful, but its account currency, instrument specification, and contract size must be correct.
5. Round down to the broker’s permitted increment
If the result is 0.473 lot and the broker accepts increments of 0.01, use no more than 0.47 lot. Rounding to 0.48 would exceed the intended price-risk calculation.
Before submitting the trade, recalculate the loss using the rounded size.

Place the Stop First, Then Size the Trade
A common mistake is choosing a preferred lot size and moving the stop until the estimated loss fits the account. This reverses the process.
The correct sequence is:
- Identify the setup.
- Define the price-based invalidation point.
- Measure the stop distance.
- Calculate the permitted position size.
- Reject the trade if minimum size or execution conditions make the risk impractical.
Swing structure, BOS, and CHoCH
Market-structure terminology is not standardized. Traders should document the definitions used by their own framework.
A Break of Structure, or BOS, usually describes price breaking a significant swing in the direction of the prevailing structure. In an uptrend, that may mean breaking above a prior swing high. In a downtrend, it may mean breaking below a prior swing low.
A Change of Character, or CHoCH, usually describes an initial break against the prevailing swing sequence. For example, a break below a protected higher low may be labelled a bearish CHoCH within an existing bullish structure.
The distinction is contextual:
- BOS generally supports continuation of the structure being tracked.
- CHoCH signals a possible transition.
- A later BOS in the new direction may provide additional structural evidence.
- Some frameworks use “market structure shift” instead of CHoCH.
- Some require a candle close; others count a wick.
- Neither BOS nor CHoCH guarantees continuation or reversal.
Liquidity sweeps can resemble structural breaks
Suppose hypothetical EUR/USD structure contains:
- Higher low: 1.1000
- Higher high: 1.1100
- Price trades briefly to 1.0988, then closes back above 1.1000
A wick-based method might call the move a bearish CHoCH. A close-based method might treat it as a liquidity sweep because price reclaimed the broken level. “Liquidity” is inferred from price behaviour and expected order concentration; traders generally cannot observe every resting order in the decentralized spot FX market.
Now suppose price forms a lower high at 1.1020 and later breaks below 1.0988. That second break could be labelled a bearish BOS within the newly developing bearish structure.
A hypothetical short entry at 1.0980 with a stop above 1.1020 has a 40-pip stop. With a $100 price-risk budget and an assumed EUR/USD value of $10 per pip per standard lot:
$100 ÷ (40 × $10) = 0.25 lot
Using a 20-pip stop solely to trade 0.50 lot would double the size but might place the stop inside the structural invalidation area. The chart determines the stop; the risk budget determines the size.

Why the Actual Loss Can Exceed Planned Risk
A stop-loss calculation estimates the loss under specified execution assumptions. It is not a guarantee.
Potential additions include:
- Bid–ask spread
- Commission
- Adverse slippage
- Financing or swap charges
- Currency-conversion costs
- Weekend or news-driven gaps
- Partial fills or delayed execution
Investor.gov explains that a stop price is a trigger rather than a guaranteed execution price; once triggered, a stop order can fill materially away from that price in a fast market. The cited bulletin addresses securities orders, so traders should also check the specific Forex order and execution terms supplied by their broker. (Investor.gov, 2017)
Planned versus realized risk
Consider this hypothetical outcome:
| Component | Loss |
|---|---|
| Price movement to intended stop | $100 |
| Commission | $4 |
| Spread not included in the original calculation | $3 |
| Adverse slippage | $8 |
| Total realized loss | $115 |
On a $10,000 account, the planned risk was 1%, but the realized loss was 1.15%.
A better process is to estimate trading costs before entry and reserve part of the risk budget for them. If historical records suggest approximately $15 of total execution costs and the absolute account-risk limit is $100, only $85 should be allocated to the price movement.
Do not create false precision. Slippage can exceed its historical average, especially around news or when liquidity deteriorates.
A large market can still produce poor retail execution
The BIS reported average global OTC FX turnover of $9.5 trillion per day in April 2025, 27% above April 2022. Its preliminary September 2025 release had reported $9.6 trillion and 28% growth; the later analytical release used the revised figures. (BIS Quarterly Review, 2025; BIS preliminary release, 2025)
Large aggregate turnover does not guarantee that a retail order will fill at its stop. Liquidity varies by currency pair, time, venue, order size, broker model, and market conditions.

Control Total Open Risk, Not Just One Trade
Individual risk limits can create a false sense of diversification.
Portfolio heat is the combined planned loss if all open positions reach their stops. If three independent positions each risk 1%, simple portfolio heat is 3%. If the positions share the same driver, the practical concentration may be worse than the trade count suggests.
Three positions can express one USD trade
Consider:
- Long EUR/USD
- Long GBP/USD
- Short USD/CHF
Each position carries significant short-US-dollar exposure. If all three risk 1%, an adverse dollar move could affect them together. Calling them three separate setups does not remove the common currency risk.
A trader could instead establish a risk-per-idea cap:
| Position | Standalone risk | Adjusted risk within USD theme |
|---|---|---|
| Long EUR/USD | 1% | 0.30% |
| Long GBP/USD | 1% | 0.25% |
| Short USD/CHF | 1% | 0.20% |
| Total | 3% | 0.75% |
These figures are hypothetical. The principle is to divide one thematic risk budget among correlated expressions.
The same rule applies to split entries and pyramiding. Three entries in one EUR/USD setup should not automatically receive three full risk allocations.

When Should You Reduce Risk?
Risk adjustments should follow written rules, not the emotion created by the last trade.
| Condition | Possible rule-based response |
|---|---|
| New or materially changed strategy | Use the lowest practical risk or paper trade |
| Drawdown exceeds the tested normal range | Reduce risk and investigate |
| Several correlated trades are open | Divide the risk budget among them |
| Spread or slippage is unusually high | Reduce size or do not trade |
| Major scheduled event is approaching | Reduce exposure, close, or stand aside |
| Daily loss limit is near | Stop opening new positions |
| Execution errors are recurring | Pause live trading and correct the process |
Reducing risk during drawdown
One illustrative policy might use:
- Normal risk: 0.50%
- Reduced risk after a 5% drawdown: 0.25%
- Pause and review after an 8% drawdown
- Restore normal risk only after the cause is understood and predefined recovery conditions are met
Those thresholds are examples, not universal standards. The purpose is to decide before stress affects judgment.
“High conviction” is not enough
Confidence is not a measured probability. Increasing from 0.5% to 2% because a setup “looks perfect” quadruples account risk without proving that its expected return has quadrupled.
If setup tiers affect size, those tiers should have:
- Objective definitions
- Separate historical samples
- Results after realistic costs
- Predefined maximum risk
- Ongoing out-of-sample monitoring

Build a Personal Risk-per-Trade Rule
A written policy should answer five questions before a trade is opened.
1. What drawdown can the account tolerate?
Set financial and psychological limits. Capital required for essential expenses should not be trading capital.
2. What does the strategy evidence show?
Record:
- Win rate
- Average winning and losing trade
- Expectancy after costs
- Maximum historical losing streak
- Maximum historical drawdown
- Performance by market condition
- Planned versus realized loss
Treat backtests as estimates. Results can be distorted by overfitting, survivorship bias, unrealistic spreads, and missing slippage.
3. What are the baseline and reduced-risk levels?
An illustrative policy could state:
I risk 0.5% of current equity under normal conditions and 0.25% when the strategy is in a predefined drawdown. Total open risk may not exceed 1.5%, and correlated positions may not exceed 0.75% collectively.
These figures must be adapted to the strategy, capital, jurisdiction, and loss limits.
4. When must trading stop?
Define daily, weekly, and strategy-level thresholds. Include floating losses, not only closed trades, when calculating total exposure.
5. How will execution be audited?
For every trade, record:
- Intended risk in account currency and R
- Entry, stop, and position size
- Estimated costs
- Actual exit and realized result
- Slippage
- Reason for any deviation
Pre-trade checklist
- Is account equity updated?
- Is the stop based on invalidation?
- Is the stop distance measured from the executable entry price?
- Is the pip value correct for the account currency?
- Are spread, commission, and slippage considered?
- Has the lot size been rounded down?
- Are correlated positions included?
- Is important scheduled news approaching?
- Does the trade fit every daily and account-level limit?
- Can the full loss be accepted without moving the stop?

Common Risk-per-Trade Mistakes
| Mistake | Why it is dangerous | Corrective action |
|---|---|---|
| Using the same lot size on every trade | Stop distances and pip values differ | Recalculate size for every setup |
| Using balance while equity is lower | The percentage understates current risk | Base the calculation on current equity |
| Choosing position size before the stop | Encourages arbitrary stop placement | Define invalidation first |
| Rounding size upward | Exceeds the intended loss budget | Round down to a permitted increment |
| Moving the stop farther away | Increases loss after entry | Reduce or close according to a written rule |
| Increasing size after losses | Accelerates drawdown and revenge trading | Maintain or reduce predefined risk |
| Sizing by confidence | Confidence does not prove an edge | Use evidence-based setup rules |
| Ignoring correlated trades | Several stops may be hit by one event | Cap total risk per currency theme |
| Assuming the stop guarantees the loss | Gaps and slippage can increase the fill loss | Include a buffer and monitor realized risk |
| Confusing margin with risk | Permitted exposure can be much larger than sensible exposure | Calculate loss at the stop independently |
Frequently Asked Questions
No percentage is inherently safe. At exactly 1% fixed-fractional risk, ten consecutive full losses would reduce equity by approximately 9.56% before costs and slippage. Whether that is tolerable depends on the strategy, total exposure, execution, and personal circumstances.
It can be. Ten consecutive losses at 2% would reduce equity by approximately 18.29% before costs. A beginner or trader without a representative live record may prefer 0.25%–0.5%, or simulation, while testing the process.
Fixed-fractional sizing never reaches zero mathematically because the monetary risk declines with equity. That does not mean an account can remain practically tradable indefinitely. Ten consecutive 1% losses leave approximately 90.44% of starting equity; 15 leave approximately 86.01%, excluding costs.
Current equity is generally the more conservative reference because it includes open profit and loss. Using balance can understate risk when existing positions have unrealized losses.
No. A stop is an exit instruction triggered at a specified level, but the execution price may be worse during a gap or fast market. Commission, spread, financing, and currency conversion can also make realized loss larger than the price-risk estimate.
Conclusion: Make Survival the First Sizing Goal
The best risk per trade is not the largest percentage an account can technically support. It is a deliberately conservative amount that lets the trading process withstand mistakes, losing streaks, changing conditions, and imperfect execution.
Start with the trade’s invalidation level. Convert a predefined risk budget into position size, allow for costs, and check total correlated exposure. If the calculation produces an unacceptable loss or impractical position, skip the trade.
CTA: Before placing your next order, write down the intended loss in both account currency and percentage terms. After the trade closes, compare that figure with the realized result. The difference is one of the most useful risk-management measurements in a trading journal.
Financial Risk Disclaimer
Forex and CFD trading involves substantial risk and may not be suitable for every investor. Leverage can magnify losses as well as gains. Stop-loss orders, position-sizing formulas, regulatory protections, and negative-balance policies do not eliminate market, execution, counterparty, or gap risk. Examples in this article are hypothetical and provided for education only; they are not investment advice, trading signals, or profit projections. Past and backtested performance does not guarantee future results. Verify current broker specifications and local regulations, and consider obtaining advice from an appropriately authorized financial professional before trading.